
Pricing Options with Monte Carlo in NumPy — Verified Against Black-Scholes
Black-Scholes gives you a closed-form price for a vanilla European option in one line — so why bother simulating? Because the moment an option’s payoff depends on the path (Asian, lookback, barrier) or you add non-linearity (American exercise, Vol surfaces, XVA), the formulas stop existing and Monte Carlo keeps working.
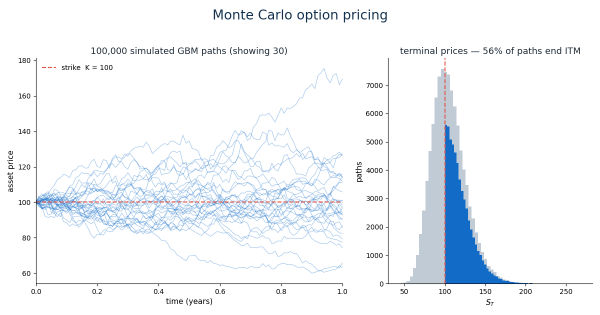
In this post we build a complete Monte Carlo pricer from scratch in NumPy, verify it against Black-Scholes, then extend it to path-dependent payoffs and Greeks. Every number shown comes from a single run with a fixed seed (numpy.random.default_rng(42)) — you should be able to reproduce all of them.